Does Repair End a Diminished-Value Claim in Albuquerque?
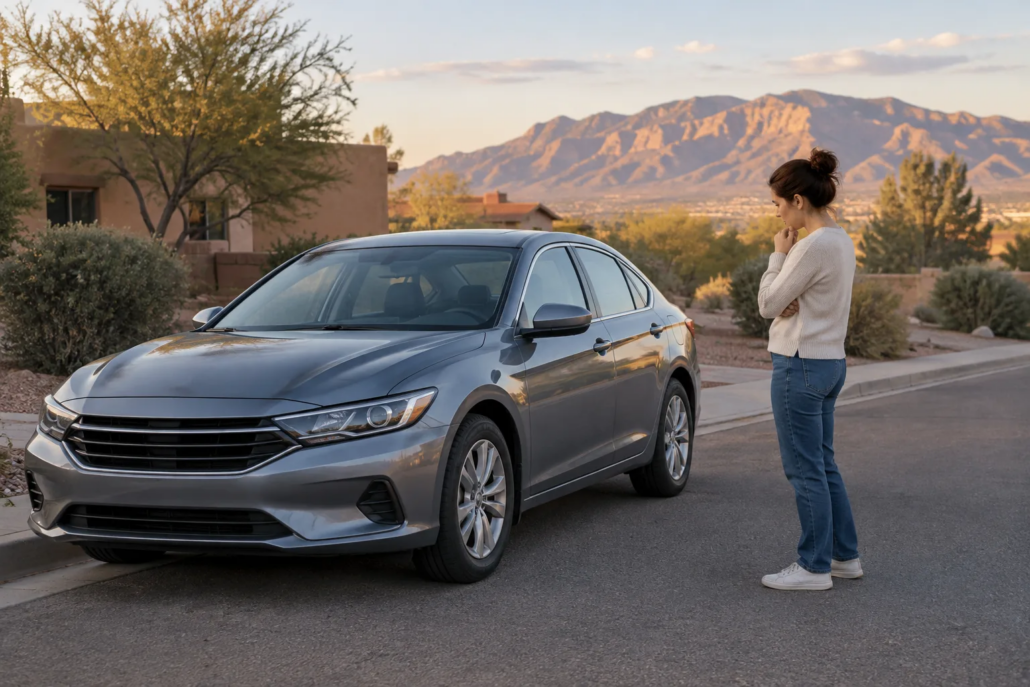
A repaired car may look whole again, but its accident history can still affect what a future buyer is willing to pay. That difference is the subject of a diminished-value claim in Albuquerque: an effort to address a possible loss in market value that remains after repairs, separate from the cost of fixing the vehicle. Whether that issue is relevant depends on the facts, the insurance coverage involved, and how the loss is evaluated.
The Crecca Law Firm helps Albuquerque crash-involved vehicle owners understand the property-damage issues that may arise after a collision. This guide explains how diminished value differs from repair costs, what records may help document a vehicle’s condition and repair history, and what questions to ask an insurer about its review. It also describes why a repaired vehicle is not automatically disqualified from a value-loss evaluation, while making clear that no particular claim or payment is assured.
How a Diminished-Value Claim in Albuquerque Differs From Repair Costs
A repair estimate or invoice measures the work and parts needed to restore a vehicle. Diminished value, by contrast, concerns a possible reduction in the vehicle’s market value after repairs. A car may be repaired carefully and function as intended, yet some potential buyers may still place less value on it because its history shows collision damage.
The amount spent on repairs does not, by itself, establish the amount of any resale-value loss. A substantial repair bill does not automatically mean the vehicle lost the same amount in market value. Likewise, a relatively modest repair does not prove that no value loss exists. An evaluation may consider the vehicle’s pre-crash condition, age, mileage, make and model, the nature of the damage, repair quality, and evidence of comparable market values.
A repaired vehicle may still have a value-loss question
Repairing the car does not erase its repair history. The question is whether reliable information supports a difference in market value—not simply whether the car was damaged or whether repairs were completed. A vehicle’s age, prior condition, damage location, and the quality and scope of repairs may all matter. An insurer or other evaluator may also use different assumptions or valuation methods, so it can be useful to ask how a conclusion was reached.
Diminished value is not a total-loss valuation
This discussion concerns a vehicle that has been repaired, or can be repaired, but may still have lower resale value. A total-loss valuation instead addresses a vehicle an insurer considers uneconomical to repair under the applicable claim process. The questions and valuation evidence are different. For a separate explanation of how insurers value a vehicle declared a total loss, see the firm’s guide to total-loss claims.
What Records May Support a Post-Repair Vehicle Value Claim?
Useful records can help show what the vehicle was like before the crash, what damage occurred, what repairs were performed, and its condition afterward. In Albuquerque, as elsewhere in New Mexico, the available information may vary depending on the vehicle and the repair process. Keep original copies where possible, and note when and how photographs or reports were created.
Records that may help an evaluator understand the vehicle and its repair history include:
- Photos or video showing the vehicle before repairs, including damage from different angles.
- The repair estimate, final itemized invoice, parts information, and documentation of supplemental work.
- Inspection findings, repair-facility notes, and any available alignment or calibration reports.
- The vehicle’s mileage, maintenance history, prior condition, and records of earlier damage or repairs.
- Information showing the vehicle’s condition after repairs, such as a follow-up inspection or clear photographs.
- Relevant insurer letters, claim evaluations, and communications about the vehicle’s value.
For additional detail on how alignment reports can document post-repair value loss, consider how technical records may help explain repair work and vehicle condition. Market comparisons may also be relevant, but asking prices in online listings are not necessarily completed sale prices. Any comparison is more useful when it accounts for factors such as model, trim, year, mileage, condition, location, and accident history.
If repairs have not started, the damage may be harder to document once the vehicle is fixed. A vehicle owner may want to ask the insurer about an inspection and preserve available photos and estimates before work begins. The firm’s overview of steps to consider before repairing a crash-damaged car discusses that timing issue. Repair and safety decisions remain specific to the situation; documentation should not be treated as a reason to delay necessary work without considering the circumstances.
What to Ask the Insurer About Its Diminished-Value Review
Insurance policies, claim types, and the facts of a collision can affect how a value-loss issue is considered. In New Mexico, the route for raising the issue may differ depending on whether the request involves the other driver’s insurer or the vehicle owner’s own policy. Policy language and applicable law matter, and requirements can vary by location or change over time. An insurer’s process is not necessarily the same in every claim.
To understand the review, a vehicle owner can ask the insurer questions such as:
- Does the insurer consider a diminished-value request under this claim or policy, and what terms or requirements apply?
- What records does the reviewer need, and can the vehicle be inspected before or after repairs?
- What valuation method, comparable vehicles, and assumptions will be considered?
- Does the evaluation account for the vehicle’s pre-crash condition, mileage, repair history, and completed work?
- Can the insurer provide its reasoning and supporting information in writing?
- If there is an offer or proposed resolution, what does accepting it release, and are any deadlines or policy conditions relevant?
Keep copies of the questions and responses, along with any valuation report or offer. If the insurer’s assessment differs from other information about the vehicle, identifying the specific assumptions or records in dispute can make the issue clearer. A lawyer may be able to review the claim’s circumstances and explain potential options, but an evaluation does not guarantee that an insurer will agree or that compensation will be available.
Frequently Asked Questions
Can I raise diminished value if I was not at fault?
Fault may be relevant to which claim or coverage applies, but it does not by itself establish the vehicle’s loss in market value. The facts, insurance terms, and applicable New Mexico law may affect whether and how the issue can be presented. An insurer may also examine the repair history and valuation evidence. A licensed attorney can assess how those considerations relate to a particular collision.
Does every accident reduce a car’s resale value?
No. An accident does not automatically establish a measurable reduction in resale value. The vehicle’s condition before the crash, the type and extent of damage, repair quality, age, mileage, and market evidence may all be relevant. Some vehicles may show little or no supported difference, while others may warrant closer evaluation. The repair bill alone does not answer the market-value question.
Can I make a diminished-value request after selling my car?
Selling a vehicle does not necessarily answer whether a value-loss issue can be considered, but it may affect what evidence is available. Sale records, pre-sale condition information, repair documents, and valuation material may help explain the vehicle’s value. The effect of a sale and any applicable deadlines can depend on the claim, policy, and circumstances. Consider getting advice specific to the situation before relying on general information.
Are online vehicle-value estimates enough to show diminished value?
An online estimate can be one source of information, but it may not account for the vehicle’s specific damage, repairs, prior condition, or accident history. Listings may show asking prices rather than completed sales, and broad valuation tools can use different assumptions. A reviewer may want more tailored comparisons or repair documentation. Ask the insurer what evidence it considers and how it weighs that information.
How The Crecca Law Firm Can Help
The Crecca Law Firm is dedicated to helping Albuquerque vehicle owners understand the property-damage questions that can follow a crash. The firm can review the available repair and valuation records, help clarify what an insurer’s review addresses, and discuss how New Mexico law and the relevant policy may affect potential options. Each situation depends on its own facts, and no particular result can be promised.
If you have questions about a repaired vehicle’s possible loss in resale value, contact The Crecca Law Firm to request a free consultation or case evaluation. The team is ready to evaluate your situation and explain the next steps that may be available.
Disclaimer: The information in this article is for educational purposes only and does not constitute legal advice. Laws vary by location and may have changed since publication; contact an attorney licensed in New Mexico for advice specific to your situation.


Leave a Reply
Want to join the discussion?Feel free to contribute!