The Crecca Law Firm
  • Home
  • About Us
  • Practice Areas
    • Asbestos Cases
    • Bad Faith Insurance
    • Bicycle Accidents
    • Brain and Head Injuries
    • Burn Injuries
    • Business Litigation
    • Car Accident
    • Medication & Drug Liability
    • Dog Bite
    • Drunk Driving Accidents
    • Motorcycle Accidents
    • Nursing Home Negligence
    • Pedestrian Injuries
    • Personal Injury
    • Slip & Fall Accidents
    • Trucking Accidents
    • Uninsured Motorist
    • Wrongful Death
  • Blog
  • News
  • Contact Us
  • (505) 766-9999
  • Menu Menu
Car accident lawsuit process in Albuquerque discussed during a legal consultation

What Might Discovery Ask in an Albuquerque Lawsuit?

October 9, 2026

After an Albuquerque car crash, an insurance claim may not resolve every disagreement. If a lawsuit is filed, the car accident lawsuit process in Albuquerque moves into a formal court phase, where each side responds to the allegations and may exchange information. Filing does not mean a trial will happen right away—or that a particular outcome is assured. The Crecca Law Firm helps injured people understand the procedural questions that can arise as a case develops. The stages and timing depend on the facts, the court, and the issues in dispute.

This guide explains what may happen after filing: service of the lawsuit, the defendant’s response, discovery, settlement discussions, and preparation for trial. It also describes the kinds of information an injured person may be asked to provide, so the process is less of a mystery. This is general information, not a prediction of how any individual case will proceed.

What the car accident lawsuit process in Albuquerque may involve after filing

Filing a complaint starts the court case, but the defendant generally must also receive formal notice. This is called service. The complaint identifies the parties and outlines the claims and requested relief; it is not, by itself, proof that the allegations are true. Rules and deadlines can depend on the court and the circumstances, so the parties’ attorneys typically monitor the applicable requirements.

Service and the defendant’s response

After service, the defendant may respond to the complaint, raise legal defenses, or in some circumstances make a motion asking the court to decide a particular issue. A response is not necessarily an admission or a denial of every factual detail. If there are multiple defendants, each may have separate counsel and may respond differently. The court’s role at this stage is to manage the case and address procedural disputes, not to decide every fact immediately.

Many civil cases arising in Albuquerque are handled in the Second Judicial District Court in Bernalillo County, but the proper court and location depend on matters such as jurisdiction and venue. New Mexico court procedures can change, and the right steps depend on the claims involved. An attorney can explain the deadlines and orders that apply to a particular case, including whether a hearing is scheduled or a preliminary issue needs attention.

Discovery in a New Mexico auto accident lawsuit

Discovery is the formal exchange of relevant information between parties. It helps each side understand the evidence and disputed issues before trial. Depending on the case, discovery may include written questions, requests for documents, requests to inspect relevant items, and depositions, in which a person answers questions under oath. Not every case uses every tool, and the scope can be disputed or limited by the court.

An injured person may be asked about the crash, prior or subsequent injuries relevant to the claims, treatment, work, and how the incident affected daily activities. Requests may also seek records such as photographs, communications, medical information, and income documentation. For example, records that can support a lost-wage claim after an Albuquerque crash may help explain claimed income loss. Treatment records and provider opinions may also relate to evidence supporting future medical costs after an Albuquerque crash.

Discovery can examine fault as well as losses. Parties may compare driver accounts, photographs, vehicle damage, and other relevant evidence. When responsibility is disputed, how New Mexico comparative fault may affect a car accident claim can help explain why evidence about each person’s actions matters. Responses should be complete and truthful, but the proper scope of a request may depend on the circumstances; counsel can explain what is being requested and address objections where appropriate.

Settlement discussions and preparing for trial

A lawsuit can continue toward trial while the parties discuss settlement. Negotiations may occur at different points, including after discovery provides a clearer picture of the evidence. Parties may disagree about who caused the collision, whether particular losses are supported, or how future effects should be evaluated. These disagreements can influence discussions; readers can review common reasons an Albuquerque crash settlement offer may seem too low for additional context.

If the parties reach an agreement, the case may resolve without a trial. Before accepting terms, it is important to understand what claims the agreement addresses and what rights may be affected. In particular, consider what an Albuquerque crash settlement release may resolve. Whether an offer makes sense depends on case-specific facts and legal advice; no negotiation or filing guarantees a particular result.

If no agreement is reached, the court may set deadlines and hearings to prepare the case for trial. This can involve identifying witnesses and experts, organizing exhibits, clarifying which facts remain disputed, and addressing evidentiary or procedural motions. Trial preparation is not just a courtroom presentation: it also requires evaluating what evidence is admissible and how each side intends to prove its position. Even as these steps proceed, settlement may remain possible. The court’s schedule and orders help determine the sequence, so timelines vary.

Frequently Asked Questions

Does filing a car accident lawsuit mean there will be a trial?

No. Filing starts a court case, but the parties may resolve it through settlement or another court-approved resolution before trial. Some cases also end after a court rules on a particular issue. Whether resolution is possible depends on the evidence, legal issues, and the parties’ decisions. An attorney can explain the options and risks relevant to a particular case without promising a result.

How long can the post-filing process take?

There is no single timeline for every case. The number of parties, complexity of the evidence, discovery needs, court scheduling, and any motions can affect how long litigation takes. A case with disputed responsibility or extensive claimed losses may require more information to be exchanged. The court’s scheduling orders and developments in the case provide a more useful guide than a general estimate.

Will I have to answer questions under oath?

Possibly. A deposition is one discovery tool, and a party or witness may be asked to give sworn answers about relevant issues. The subjects and format depend on the case, and attorneys may attend. A person responding to questions should understand the process and ask counsel about preparation, objections, and the scope of questioning. Whether a deposition is needed is case-specific.

Will I need to go to court soon after the lawsuit is filed?

Not necessarily. Filing and service are procedural steps, and a court appearance may not be scheduled immediately. The court may later set hearings, conferences, or trial dates, depending on the case and its orders. Attorneys generally help clients understand whether their attendance is required and what a particular proceeding concerns. The schedule in an individual case is more reliable than a general expectation.

How The Crecca Law Firm Can Help

The Crecca Law Firm is dedicated to helping injured people understand the decisions and information requests that may arise during litigation. A lawyer can explain the complaint and response, help assess discovery requests, discuss how evidence relates to disputed issues, and clarify the next steps set by the court. The process can differ from one case to another, so guidance should be based on the specific facts and applicable New Mexico procedure. If you have questions about an Albuquerque crash lawsuit, contact The Crecca Law Firm to request a free consultation or case evaluation and discuss your situation.

Disclaimer: The information in this article is for educational purposes only and does not constitute legal advice. Contact a qualified attorney licensed to practice in New Mexico for advice specific to your situation.

https://thecreccalawfirm.com/wp-content/uploads/2026/10/what-might-discovery-ask-in-an-albuquerque-lawsuit-5798-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-09 09:58:372026-10-09 09:58:37What Might Discovery Ask in an Albuquerque Lawsuit?
Several injured people and one driver’s vehicle illustrate Albuquerque car accident policy limits

When Should Multiple Claimants Review Albuquerque Limits?

October 9, 2026

A crash involving more than one injured person can raise a difficult coverage question: is there enough insurance for all the claims? In Albuquerque, multiple claimants car accident policy limits may mean that one driver’s liability coverage is available to address claims from several people, subject to the policy’s terms and applicable law. The total losses people report can be greater than the coverage available.

The Crecca Law Firm helps people understand the questions that can arise during an injury claim. If an insurer says there are other claimants, it may be useful to understand what “shared limits” means, what information the insurer can provide, and what facts may matter before considering a resolution. This article discusses how policy limits work, what to ask, and why claim timing and individual losses can differ.

How multiple claimants may share Albuquerque car accident policy limits

A liability policy does not necessarily provide a separate full limit for every person injured in a collision. Depending on the policy, coverage may include a per-person limit and a larger per-accident limit. The per-person amount can cap what is available for one injured person, while the per-accident amount can cap the insurer’s total payment for bodily injury claims from that event. Policy language and the circumstances of the crash matter.

For example, several people may each have medical expenses, lost income, or other claimed losses. Their combined claims could exceed the policy’s per-accident limit. In that situation, the available liability coverage may not match the total amount claimed. That does not mean each person automatically receives an equal share; the way claims are evaluated or resolved depends on relevant facts, policy terms, and applicable New Mexico law.

What does “other claimants” mean?

When an adjuster mentions other claimants, ask whether that refers to people who have reported injuries, formally presented claims, or are otherwise known to the insurer. Those categories may not be the same. The insurer may also have limits on what it can disclose about other people’s private information, so a request for details may not produce names or complete claim files.

It can still be helpful to ask what coverage limit applies, whether the insurer believes the per-accident limit may be involved, and what information supports that view. Albuquerque claimants should not assume that a brief reference to “other claims” explains how much coverage remains or how a proposed resolution would affect their own claim.

What should you ask and gather before discussing resolution?

Before evaluating a proposed resolution, a claimant may want to understand the available coverage and the information the insurer is using. The details vary, but questions to consider discussing with the insurer or an attorney include:

  • What are the applicable per-person and per-accident bodily injury limits?
  • Are there other known injury claims arising from this collision, and what can the insurer share about their status?
  • Has the insurer identified any other potentially applicable liability policies?
  • What information or documents does the insurer still need to evaluate this claim?
  • Would a proposed payment resolve only this claimant’s claim, or are there other terms to understand?

A claimant’s records can help explain their own losses, even though they do not establish what another person’s claim is worth. Depending on the situation, relevant material may include treatment records and bills, wage or income information, and documentation of other claimed expenses. For practical information about organizing medical bills after an Albuquerque car accident, see the firm’s related guide.

If the at-fault driver’s coverage may not be enough, a person’s own insurance could be relevant. The availability and application of uninsured or underinsured motorist coverage depend on the policy and circumstances. A discussion of reviewing uninsured and underinsured motorist coverage in Albuquerque can help explain what coverage questions may be worth raising.

Why other claims and developing information can affect timing

Several claims from one collision may require the insurer to review different evidence and circumstances. One person’s treatment or assessment may still be developing while another claimant has different records or losses. The insurer may also be gathering information about the collision, the number of claims, and the policy’s coverage. These differences can affect when a person has enough information to evaluate a proposed resolution; there is no single timetable that applies to every Albuquerque accident claim.

A settlement offer should be understood in context. The amount of insurance available is not automatically the same as the amount of a particular person’s claim, and a gross settlement amount is not always the amount that person ultimately keeps. Depending on the facts, medical liens or reimbursement obligations may affect net recovery. For more on how medical liens can affect an Albuquerque settlement recovery, see the firm’s guide.

Before agreeing to resolve a claim, it may be important to understand what claims or rights the release covers and whether the information available is sufficient to evaluate the terms. The claim’s investigation, ongoing care, and insurer review can all matter. Read more about factors that shape an Albuquerque car accident claim timeline. In New Mexico, the policy and applicable state law guide coverage questions; laws and procedures can vary by location and may change.

Frequently Asked Questions

Does each injured person get the same amount from one driver’s policy?

Not necessarily. A policy may set both per-person and per-accident limits, and a claim’s circumstances and supporting information can differ from another person’s. There is no general rule that every claimant automatically receives an equal portion of the available coverage. How claims are evaluated or resolved depends on the policy, the facts, and applicable New Mexico law. An attorney can review the terms and circumstances relevant to a particular claim.

Can the insurer tell me who the other claimants are?

An insurer may be able to confirm that other claims are known, but it may not provide names or private details about other people. What it can disclose can depend on the circumstances and privacy considerations. You can ask what the insurer means by “other claimants,” whether the claims are reported or formally presented, and what information it can share about the coverage situation without revealing protected personal details.

Does the driver’s policy limit include vehicle damage claims too?

Property damage coverage and bodily injury coverage are commonly addressed under separate parts of an auto policy, with their own terms and limits. The exact policy language matters, and a collision can involve both injury and vehicle-damage claims. If you are trying to understand which limit applies to an injury claim, ask the insurer to identify the relevant coverage and explain whether it is discussing bodily injury limits or another part of the policy.

Could my own insurance matter if several people are injured?

Possibly. Depending on the policy and the facts, your own uninsured or underinsured motorist coverage may be relevant if the at-fault driver’s available liability coverage is insufficient. Coverage is not automatic in every situation, and policy terms, eligibility, and applicable law matter. A review of your policy can help clarify what protections may apply and what notice or claim requirements are relevant.

How The Crecca Law Firm Can Help

The Crecca Law Firm is dedicated to helping injured people understand the coverage and claim questions that can follow a collision. When an insurer says there are multiple claimants, the firm can review the available information, explain questions about policy limits, and discuss what documentation may help describe your losses. Each claim depends on its own facts, policy language, and applicable law. If you have questions about a crash in Albuquerque, contact The Crecca Law Firm to request a consultation or case evaluation and discuss your situation.

The information in this article is for educational purposes only and does not constitute legal advice. Contact a qualified attorney licensed in New Mexico for advice specific to your situation.

https://thecreccalawfirm.com/wp-content/uploads/2026/10/when-should-multiple-claimants-review-albuquerque-limits-5776-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-09 08:55:332026-10-09 08:55:33When Should Multiple Claimants Review Albuquerque Limits?
Albuquerque car accident lawyer contingency fee discussion at a consultation table

What Fees Does an Albuquerque Car Accident Lawyer Charge?

October 8, 2026

After a crash, it can be hard to focus on legal paperwork while also managing repairs, missed work, and calls from insurers. Before hiring an Albuquerque car accident lawyer, many people want to know what they will pay—and whether expenses come out of a settlement separately from the lawyer’s fee. A contingency fee agreement puts those terms in writing, but the details can differ from one agreement to another.

The Crecca Law Firm can help explain the kinds of provisions people commonly encounter. This guide outlines what to ask about the fee percentage, case expenses, settlement calculations, and what the agreement says if there is no recovery. Reviewing those points before representation begins can help you understand the financial terms and ask follow-up questions. This is general information about New Mexico matters; laws and procedures vary by location and may change.

What Should an Albuquerque Car Accident Lawyer’s Contingency Fee Agreement Explain?

A contingency fee is generally tied to a recovery: the lawyer’s fee is calculated under the formula set out in the agreement rather than billed as a conventional hourly fee. There is no single percentage that applies to every case. The written terms should identify the percentage or formula, when it applies, and whether it changes if the claim reaches a different stage, such as filing a lawsuit or going to trial.

Ask how the percentage is calculated

Ask whether the fee is calculated from the gross recovery before expenses and other deductions, or from a defined amount after certain deductions. The agreement should make the calculation understandable, including what counts as a recovery and how any different stage-based percentages work. For a broader local overview, see a guide to Albuquerque car accident lawyer costs.

Separate the fee from case expenses

Attorney fees compensate the lawyer for legal services. Case expenses are amounts paid or incurred to develop or pursue the claim. Depending on the case, examples may include charges for obtaining records, expert review, filing, service of documents, or deposition transcripts. Ask which expenses may arise, who authorizes them, and whether the client may be responsible for them if there is no recovery. The agreement should explain how expenses are tracked and deducted, rather than leaving you to guess what “costs” means.

How Do Costs and Settlement Deductions Affect Your Net Amount?

A settlement figure is not necessarily the amount a client receives. A written breakdown may show the gross recovery, the attorney fee, case expenses, and any separate obligations that must be addressed. The order of calculation matters: subtracting expenses before or after calculating the fee can produce different net figures. Ask for a sample calculation using hypothetical numbers, not a prediction of what your case is worth.

Repayment claims, including some health insurance liens, are different from attorney fees and litigation expenses. They may affect the client’s net proceeds, but their existence and amount depend on the circumstances. Ask how the agreement treats those obligations and whether the lawyer will help identify or discuss them. For more detail, read about how health insurance liens can affect an Albuquerque crash settlement.

Also distinguish legal case expenses from medical bills incurred while treatment is ongoing. A fee agreement may explain legal expenses, but it does not automatically determine who pays current providers or how those bills are handled. This overview of ways to address medical bills while an Albuquerque crash claim is pending discusses that separate issue.

Before signing, consider asking:

  • Will I receive a written closing statement showing the recovery and each deduction?
  • Are expenses deducted before or after the attorney fee is calculated?
  • How are liens or other repayment claims handled, and are they included in the fee calculation?
  • Will the firm discuss significant expenses with me before incurring them?

What Should You Clarify About No Recovery and a Lawsuit?

The agreement should say what happens if the claim does not produce a recovery. Do not assume that “contingency” means you will never owe anything. One contract may say the firm absorbs certain case expenses if there is no recovery; another may assign some expenses to the client. The precise language controls, so ask the lawyer to explain which costs, if any, could remain your responsibility and whether the answer changes if representation ends before the case concludes.

Ask what expenses require your approval, how often the firm will report them, and whether you can review an itemized record. Clarify whether the agreement covers an appeal or other work beyond the initial claim, or whether a separate written arrangement would be needed. These questions can prevent an unexpected difference between your understanding and the signed terms.

A lawsuit can involve additional steps and expenses, including filing, discovery, and depositions. Ask whether the fee percentage or expense policy changes if the case moves into litigation, and when any change takes effect. The explanation of the steps after filing an Albuquerque crash lawsuit can help put those potential stages in context. Albuquerque claims that proceed in court are handled under applicable New Mexico and local procedures; the proper court depends on the case. Reading the agreement carefully and asking direct questions is a practical way to understand the arrangement before work begins.

Frequently Asked Questions

Is a contingency fee percentage the same for every Albuquerque car accident case?

No. The percentage and the way it is calculated are terms to confirm in the specific written agreement; there is not one percentage that applies to every case. Some agreements may describe different percentages at different stages. Ask the lawyer to explain when each rate would apply, what amount it is based on, and how expenses and other deductions affect the final calculation.

Can I ask for a written estimate of possible case expenses?

You can ask how the firm tracks expenses, which costs may arise, and whether it can provide an estimate or explain common expense categories. Actual costs depend on how a claim develops, so an estimate may not be a final amount. Ask whether you will be consulted before substantial expenses are incurred and whether you will receive an itemized accounting.

Does the contingency fee agreement cover medical bills?

Not necessarily. The agreement primarily describes the lawyer’s fee and the handling of legal case expenses. Medical bills and repayment claims are separate issues, and their treatment can depend on the facts, insurance coverage, and other obligations. Ask the lawyer to distinguish these categories and explain which questions the fee agreement answers and which require separate review.

Can I review the fee agreement before deciding to hire the lawyer?

You can ask to review the proposed agreement and have its terms explained before deciding whether to sign. Pay particular attention to the fee formula, expenses, responsibility if there is no recovery, and what happens if representation ends or litigation begins. If a provision is unclear, ask for clarification in writing so you can consider the terms with a full understanding.

How The Crecca Law Firm Can Help

Understanding the financial terms of representation is part of making an informed choice after a crash. The Crecca Law Firm is dedicated to helping Albuquerque clients understand the claims process and the written terms that may apply to their situation. A conversation can help identify questions about fee calculations, case expenses, settlement deductions, and no-recovery provisions; the agreement itself will determine the terms of any representation.

If you have questions about a proposed agreement or a car accident claim, contact The Crecca Law Firm to request a consultation or case evaluation. The firm can listen to your concerns and discuss whether it may be able to assist.

Disclaimer: The information in this article is for educational purposes only and does not constitute legal advice. Contact a qualified attorney licensed to practice in New Mexico for advice specific to your situation.

https://thecreccalawfirm.com/wp-content/uploads/2026/10/albuquerque-car-accident-lawyer-contingency-fee-agreement-5672-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-08 09:38:272026-10-08 09:45:28What Fees Does an Albuquerque Car Accident Lawyer Charge?
Albuquerque car accident claim timeline represented by a quiet city road and a person reviewing blank paperwork

What Shapes an Albuquerque Car Accident Claim Timeline?

October 8, 2026

A crash claim can feel as though it has stopped moving when days pass without a clear update. But an Albuquerque car accident claim timeline depends on more than how quickly an insurance adjuster responds: the investigation, the course of medical care, and whether the parties agree on responsibility and losses can all matter. The Crecca Law Firm helps Albuquerque readers understand those moving parts without suggesting that every claim follows the same schedule.

There is no reliable single answer to how long a car accident claim takes in New Mexico. Some claims resolve after the relevant information is available and the parties reach agreement; others take longer because key facts or the extent of an injury remain uncertain. This guide explains the common stages, what may slow progress, and practical ways to stay informed while a claim is pending. It also distinguishes a settlement timeline from a legal filing deadline.

What Shapes an Albuquerque Car Accident Claim Timeline?

A claim usually moves through connected stages, but they do not always happen in a neat sequence. How long each takes depends on the facts, available evidence, insurance coverage, and the needs of the injured person.

Investigation and liability review

The insurer may gather information about the collision, vehicles, people involved, and reported injuries. That can include reviewing statements, photographs, vehicle damage, medical records, and the crash report. A report can be one piece of the picture; it does not automatically decide civil responsibility. For more context, read about how an Albuquerque crash report may affect a fault investigation.

If accounts conflict or the evidence is incomplete, the parties may need more time to assess what happened. Disagreement about each driver’s share of responsibility can also affect negotiations. In New Mexico, comparative fault rules after a car crash may be relevant when more than one person is alleged to have contributed to a collision.

Treatment and understanding the injury

For an injury claim, the timing of treatment and the available medical information can affect when the claim is ready for meaningful evaluation. If care is ongoing or the likely course of treatment is not yet clear, the full scope of claimed losses may remain uncertain. Documentation about evidence supporting future medical costs after an Albuquerque crash may be important to that assessment.

Why Can an Albuquerque Car Accident Claim Take Longer?

A claim can take longer when information needed to evaluate it is missing, disputed, or still developing. Common reasons include:

  • Delays in obtaining a crash report, medical records, bills, wage information, or other supporting documents.
  • Disagreement about how the collision happened or which driver was responsible.
  • Questions about available insurance coverage or the parties’ positions on the value of losses.
  • Ongoing treatment that makes it difficult to assess the extent or likely duration of an injury.
  • Negotiations that continue because the insurer and claimant do not agree on liability or damages.

These factors can overlap. For example, an unresolved fault question may require additional evidence, while ongoing care may make it premature to assess certain claimed expenses. For more on common reasons an Albuquerque car accident claim stalls, consider how missing records, disputed liability, or coverage questions can affect a review.

A claim may also move into litigation if the parties cannot resolve it through insurance discussions. Depending on the circumstances and applicable rules, a lawsuit arising from an Albuquerque collision may involve the Second Judicial District Court in Bernalillo County. Court procedures, scheduling, and the issues in dispute can add steps; filing suit does not establish how quickly a case will conclude. The appropriate forum and process depend on the particular claim.

It is also useful to separate an insurance claim’s progress from the deadline to file a lawsuit. A filing deadline is not a prediction of when a settlement should happen, and deadlines can depend on the claim’s circumstances. Learn about New Mexico deadlines for filing an Albuquerque crash claim; laws can vary by location and may change.

How Can You Stay Informed While a Claim Is Pending?

A claimant cannot control every investigation or negotiation, but clear records and communication can make it easier to understand the status of a claim. General practices that may help include:

  1. Keep a claim file. Save insurer correspondence, claim numbers, records of calls, receipts, medical bills, and documents related to time missed from work. Note when information was sent and to whom.
  2. Ask focused status questions. You can ask what information the insurer is reviewing, whether anything is outstanding, and what step is expected next. If there is no clear update, a calm written request can help keep a record of the inquiry.
  3. Track expenses as they arise. Bills may arrive before a claim is resolved. Keep copies and check what payment sources may be available; ways to manage Albuquerque crash medical bills before settlement may offer additional context.
  4. Understand what a proposed agreement covers. Reaching an agreement does not always mean funds are distributed immediately. Release paperwork and health insurance liens that may need attention after an Albuquerque settlement can affect final processing.

These steps do not guarantee faster resolution. They can help you identify unanswered questions and understand what may be holding up the next stage. If you have legal representation, ask how updates will be shared and who to contact with questions. In Albuquerque, as elsewhere in New Mexico, the relevant timeline depends on the case facts and applicable law.

Frequently Asked Questions

Is there a typical settlement timeline for a car accident in Albuquerque?

There is no single timeline that applies to every Albuquerque claim. A straightforward claim with documented losses and no significant dispute may follow a different path from a claim involving continuing treatment, questions about fault, or complex coverage issues. The time needed to gather and review information, negotiate, and complete paperwork can all vary. An attorney can discuss factors that may apply to a particular situation.

Can I settle my injury claim while I am still receiving treatment?

Whether to discuss or accept a settlement while treatment is ongoing depends on the facts and the terms of the proposed agreement. If the likely course of care or future costs are not yet clear, it may be difficult to assess the full extent of claimed losses. A settlement agreement may also have legal consequences. Consider obtaining advice from a licensed New Mexico attorney about the specific offer and circumstances.

Does filing a lawsuit mean my claim will resolve sooner?

Not necessarily. A lawsuit may create a formal court process, but it can also involve additional procedures and scheduling. The effect depends on the issues, the parties, and the applicable court process. In Albuquerque, a case may involve the Second Judicial District Court in Bernalillo County when that court is the appropriate forum. The decision and likely timing are case-specific and cannot be predicted from filing alone.

Will I receive settlement money as soon as an agreement is reached?

Not always. After an agreement, the parties may still need to complete release documents and address payment processing. In some claims, medical reimbursements or liens may also need review before funds are distributed. The timing depends on the paperwork, the parties involved, and the claim’s circumstances. Ask for an explanation of any remaining steps and keep copies of documents you sign or receive.

How The Crecca Law Firm Can Help

The Crecca Law Firm is dedicated to helping people understand the stages and questions that can affect an Albuquerque car accident claim. The team can review the information available, explain issues that may influence the timeline, and discuss ways to stay informed while a claim is pending. Every claim is different, and no particular resolution date or result can be promised. If you have questions about your situation, contact The Crecca Law Firm to request a consultation and discuss your options.

Legal disclaimer: The information in this article is for educational purposes only and does not constitute legal advice. Contact a qualified attorney licensed in New Mexico for advice specific to your situation.

https://thecreccalawfirm.com/wp-content/uploads/2026/10/albuquerque-car-accident-claim-timeline-5660-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-08 08:56:552026-10-08 09:04:15What Shapes an Albuquerque Car Accident Claim Timeline?
Albuquerque freelancer beside a car, illustrating a self-employed lost wages car accident claim

Can Albuquerque Freelancers Claim Lost Income After Crashes?

October 7, 2026

A car accident can disrupt a freelancer’s work even without a traditional employer or regular paycheck. A designer may miss a deadline, a contractor may have to turn down a project, or a delivery driver may be unable to accept trips while recovering. For Albuquerque freelancers, a self-employed lost wages car accident claim may involve showing what income was expected, what work was lost, and how the crash-related injury affected the ability to earn it. The Crecca Law Firm helps people understand the documentation issues that can arise in injury claims. This guide explains how lost income differs from ordinary wages, which records may help establish the disruption, and what to consider if an insurer questions the amount. The specific value and availability of any claim depend on the facts, evidence, and applicable New Mexico law.

How Albuquerque Freelancers Can Claim Lost Income After a Car Accident

A freelancer’s income may vary from month to month, so proving a loss often requires a fuller picture than a missed paycheck. In general, a claim may seek compensation for income connected to work a person could not perform because of crash-related injuries. That is not necessarily the same as claiming every dollar of business revenue that did not come in.

The distinction matters. Revenue is money received by a business before accounting for expenses. A claim may need to account for the income the person would likely have kept, as well as whether work was postponed, completed later, or permanently lost. A freelancer’s own records can help explain those details, but no single document automatically establishes the amount.

Lost income is not always the same as lost wages

An employee may use pay stubs and a schedule to show missed work. A self-employed person may instead need to connect a pattern of earnings and specific work opportunities to the period they could not work. The analysis may differ for an established business, a new freelance practice, or someone who combines contract work with a part-time job.

Medical information can also be relevant. Records describing work restrictions or time away from work may help explain why a project or shift could not be completed. Any claimed loss still needs to be considered in light of the individual facts and the applicable rules.

Records freelancers can use to document lost income

A useful records file combines evidence of ordinary earnings with evidence of work disrupted after the collision. Albuquerque freelancers may have documents spread across tax software, email, invoicing platforms, bank accounts, and project tools. Organizing records by time period and connecting them to the claimed interruption can make the story easier to evaluate.

Consider gathering relevant items such as:

  • Tax documents: Prior federal and state tax returns, including business schedules when applicable, can help show historical earnings. A return is useful context, but it may not capture recent growth, seasonal swings, or an unusual year by itself.
  • Invoices and payment records: Issued invoices, receipts, bank deposits, and bookkeeping reports can show completed work and payment patterns.
  • Contracts and booking records: Signed agreements, accepted project proposals, scheduled jobs, and work orders may show expected assignments and deadlines.
  • Canceled or postponed work: Client messages, cancellation notices, revised deadlines, or records of a replacement provider may help establish what changed after the crash.
  • Business records: Profit-and-loss reports, ledgers, calendars, and platform earnings summaries may help explain the business’s normal activity.
  • Medical restrictions: Relevant records from a treating provider may document limitations or missed work periods. They should be considered alongside the work records, not as a substitute for financial proof.

Together, these materials may show both a baseline and a specific interruption. For a more detailed checklist, see records that can support lost income after an Albuquerque crash.

Common proof problems and steps to avoid them

Freelance income is often irregular, and that can prompt questions about whether a claimed loss was caused by the crash or would have happened anyway. A quiet season, a client’s independent decision to cancel, or a project completed later may affect how the loss is assessed. Clear records and a consistent explanation can help distinguish these situations.

Some common documentation problems include:

  • Relying only on estimates: An estimate may be harder to assess without invoices, prior earnings, contracts, or other supporting records.
  • Claiming gross revenue as personal income: Business costs and work that was later completed may affect the calculation.
  • Leaving gaps unexplained: If income fluctuates, records from comparable periods or a clear explanation of seasonal work may provide context.
  • Separating medical and business evidence: A calendar showing missed work may be more informative when considered alongside records of work restrictions and the affected project.
  • Overlooking platform records: App-based workers may need to preserve trip history, account status, earnings, and relevant communications. Coverage questions can depend on a driver’s activity in the app at the time of a crash, which is separate from proving lost income. See insurance documentation for an Albuquerque Uber or Lyft crash.

If a claim cannot be resolved informally, a lawsuit arising from an Albuquerque collision may be handled in the Second Judicial District Court, depending on venue and the circumstances. New Mexico law governs many claims arising in the state, but legal rules can vary by jurisdiction and may change. If an insurer disputes the income calculation, why an Albuquerque crash settlement offer may undervalue income loss may help explain what issues to review alongside the rest of the documented claim.

Frequently Asked Questions

Can I claim income if I missed only some freelance work?

Possibly. A claim may involve a partial interruption, such as reduced hours, fewer assignments, or work that could not be completed on schedule. Relevant records may include the jobs affected, payments received or lost, and any later completion of the work. Whether a particular amount is recoverable depends on the evidence, the cause of the missed work, and applicable law.

How do insurers evaluate irregular freelance earnings?

There is no single record that answers every question. An insurer may consider tax documents, invoices, contracts, bookkeeping records, and the person’s prior earnings pattern, along with evidence of the work affected. Seasonal or changing income may need explanation. The person reviewing a claim may also distinguish business revenue from the income that would likely have remained after expenses.

Can a freelancer include work expected in the future?

A claimed loss involving future work may require evidence that the opportunity and expected income were reasonably supported, as well as information connecting the loss to the crash. A speculative possibility may be treated differently from an accepted contract or scheduled assignment. The analysis depends on the facts and applicable New Mexico law, so future-income questions may benefit from an individualized legal review.

What if I have both freelance clients and a part-time job?

Each source of income may need its own supporting records. Pay statements or employer information may help document missed employee work, while invoices, contracts, and business records may help explain freelance losses. Keeping the timelines distinct can make it clearer which work was affected and how. The records and rules that apply depend on the type of work and the circumstances of the collision.

How The Crecca Law Firm Can Help

The Crecca Law Firm is dedicated to helping injured people understand the issues that may affect a personal injury claim, including how self-employment and variable income can complicate proof of loss. The firm can review the available records, consider how medical restrictions relate to work disruption, and explain questions that may arise in an Albuquerque claim. No two situations are identical, and a review cannot promise a particular outcome. If a crash has affected your ability to earn income, contact The Crecca Law Firm to request a free consultation or case evaluation and discuss your circumstances.

The information in this article is for educational purposes only and does not constitute legal advice. Contact a qualified attorney licensed in Albuquerque for advice specific to your situation.

https://thecreccalawfirm.com/wp-content/uploads/2026/10/albuquerque-freelancer-lost-income-car-accident-5559-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-07 10:19:502026-10-07 10:25:22Can Albuquerque Freelancers Claim Lost Income After Crashes?
A person reviews a low car accident settlement offer in Albuquerque beside a window overlooking the Sandia Mountains.

How Do You Review a Low Albuquerque Crash Settlement Offer?

October 7, 2026

An insurer’s settlement offer may arrive as a single number, with little explanation of how it was calculated. If the amount seems low, the gap may reflect missing records, different assumptions about the collision, or losses the insurer has not included—not necessarily a final assessment of the claim. For people reviewing a low car accident settlement offer in Albuquerque, it helps to understand the figure before deciding how to respond. The Crecca Law Firm can help readers understand the kinds of issues that may matter in a claim review. This article outlines a practical framework: check what the offer assumes and covers, compare it with supporting records, identify disputed facts, and list unanswered questions before communicating with the insurer.

Review a low car accident settlement offer in Albuquerque: what assumptions drive it?

Start by looking for an explanation of the offer, not just the total. Check whether the insurer has separated injury-related losses from vehicle damage, and whether it says any part of the claim is unsupported, disputed, or still being evaluated. If the offer is described as an initial or revised amount, note what changed from any earlier evaluation and what new information the insurer considered.

Check what the offer includes

A settlement evaluation may address medical expenses, lost income, vehicle damage, and other claimed losses. The amount can also be affected by the insurer’s view of the available evidence and responsibility for the collision. A low figure is easier to assess when you can identify the assumptions behind each part. For more background on common reasons an Albuquerque crash settlement offer may be low, consider which categories the offer addresses and which it leaves unclear.

Ask whether the calculation reflects bills already submitted, whether future care is being considered, and whether any expense was excluded. Do not assume a category is included merely because you mentioned it during the claim process. Requesting an itemized explanation can help reveal where the parties’ views differ.

Separate vehicle damage from injury losses

If the offer includes a vehicle payment, review that calculation on its own. An injury settlement and a property-damage evaluation can involve different records and valuation questions. When a vehicle is treated as a total loss, details such as the vehicle’s condition and comparable values may be relevant to reviewing an Albuquerque insurer’s total-loss vehicle valuation. Keeping the two calculations distinct can make it easier to see what the offer actually resolves.

Compare the offer with records and disputed facts

Next, compare the insurer’s stated assumptions with the documents you have provided and the losses you are claiming. A useful review is specific: identify an expense, wage loss, or other item; find the supporting record; and check whether the insurer appears to have considered it. Depending on the circumstances, records may include treatment bills, visit summaries, wage or time-off documentation, photographs, repair estimates, and correspondence about the claim. For a more focused checklist, see evidence to gather when an Albuquerque crash claim is disputed.

Do not treat a difference between the offer and your records as proof of bad faith or a guaranteed error. It may reflect missing information, a disagreement about whether a loss relates to the collision, or a different evaluation of the evidence. Make a note of what the insurer says is missing or uncertain, and match each issue to the record that may address it.

Fault assumptions deserve their own review. Compare the insurer’s account of how the crash happened with your recollection, photographs, witness information, and any available crash report. In Albuquerque and elsewhere in Bernalillo County, a report may be one source of information, but it does not necessarily answer every question about civil responsibility. Learn more about how an Albuquerque crash report may affect disputed fault. If the insurer assigns some responsibility to you, ask what facts support that position and whether it has considered evidence that points another way.

List unanswered questions before responding

Before deciding whether to accept, ask questions, or provide additional documentation, write down what remains unresolved. For example, does the insurer need a particular bill or wage record? Is it relying on a statement about the collision that you believe is incomplete? Does its evaluation account for all claimed property damage? A short, organized list can keep a response focused on concrete issues rather than a general disagreement with the number.

Also consider the difference between the gross offer and what might remain after obligations tied to the claim. Health-plan reimbursement requests, provider claims, or other liens may affect net recovery, depending on the facts. For context, review how health insurance liens can affect an Albuquerque crash settlement. Avoid treating the offer’s headline amount as the same as money you would necessarily keep.

Read any proposed release carefully before signing or accepting a settlement. The document may define which claims are being resolved, so consider whether it addresses only the payment currently discussed or broader claims arising from the crash. If questions about treatment, future care, or the release’s scope remain, those are important issues to clarify. This overview explains what an Albuquerque crash settlement release may resolve.

If you decide to communicate with the insurer, a clear response can identify the offer date, the specific assumptions or missing items you question, and any supporting materials you are providing. Keep copies of communications and documents. For general process context, read about how car accident insurance settlement negotiations proceed. A response does not have to commit you to accepting or rejecting an offer; what makes sense depends on the claim, the documents, and any applicable deadlines.

Frequently Asked Questions

Does a low settlement offer mean the insurer has finished evaluating my claim?

Not necessarily. An offer may be an initial evaluation or may reflect the information the insurer has reviewed so far. Ask what records and losses were considered, whether any part remains under review, and what information the insurer says is missing. The answer can help clarify whether the disagreement concerns documentation, the value assigned to a loss, or responsibility for the collision.

Can I ask the adjuster to explain how the offer was calculated?

You can request an explanation of the categories and assumptions behind the figure. Depending on the insurer and claim, that may include asking which bills, wage records, vehicle information, or collision facts it considered. Keep the questions specific and retain the response. An explanation may help identify a documentation gap or a substantive disagreement, but it does not by itself determine what a claim is worth.

What if the insurer’s account of the Albuquerque crash differs from mine?

Make a note of the points of disagreement and compare them with available information, such as photographs, witness details, and a crash report. In Albuquerque, a report may help document aspects of a collision, but its contents may not resolve every disputed fact. An attorney can assess how the available evidence and applicable New Mexico law may affect your particular situation.

Should I accept an offer while I am still receiving care?

Whether to accept depends on the terms, the claim’s status, and your circumstances. Review what the proposed release would resolve and whether questions about ongoing or future care remain. A settlement may involve giving up claims described in the release, so consider getting advice from a qualified New Mexico attorney before deciding. Do not assume an offer can be revisited after acceptance.

How The Crecca Law Firm Can Help

The Crecca Law Firm is dedicated to helping Albuquerque crash claimants understand the issues behind an insurer’s offer. A review may include the assumptions used to calculate the figure, the records documenting claimed losses, disputed collision facts, and the terms of any proposed release. The firm is committed to fighting for clients’ rights while helping them understand options that may depend on the details of their claim. If you have received an offer and want help evaluating what it addresses, contact The Crecca Law Firm to discuss a free consultation or case evaluation.

The information in this article is for educational purposes only and does not constitute legal advice. Laws vary by location and may change; contact a qualified attorney licensed in New Mexico for advice specific to your situation.

https://thecreccalawfirm.com/wp-content/uploads/2026/10/low-car-accident-settlement-offer-albuquerque-5525-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-07 08:37:252026-10-07 08:37:25How Do You Review a Low Albuquerque Crash Settlement Offer?
Albuquerque car accident medical bills before settlement reviewed at a table

Who Pays Albuquerque Crash Medical Bills Before Settlement?

October 6, 2026

An accident claim may take time to investigate, but an emergency-room statement, ambulance bill, imaging invoice, or follow-up provider balance can arrive within weeks. So, what happens to Albuquerque car accident medical bills before settlement? Usually, the injured person must work with available payment sources while fault, insurance coverage, treatment, and damages are still being evaluated.

The at-fault driver’s liability insurer generally does not function like a health plan that pays each provider as bills arrive. A carrier may investigate responsibility and damages, but that process does not necessarily stop collection notices or make current treatment free. The Crecca Law Firm helps Albuquerque injury clients understand these moving parts and organize the information needed for an informed claim evaluation. This article explains payment options, documentation, communication with insurers, and why settlement timing matters.

Who Pays Albuquerque Car Accident Medical Bills Before Settlement?

In many New Mexico crashes, the answer depends on the injured person’s available coverage and the provider’s billing policies. There may not be one automatic payer. Understanding who may pay medical bills after a New Mexico car accident can help explain why a liability claim and medical billing process often move on separate tracks.

Potential sources of payment

Depending on the circumstances, a person may need to investigate:

  • Health insurance, including the plan’s ordinary deductibles, copayments, or coinsurance.
  • Medical payments coverage, if available under an applicable auto policy.
  • A provider’s payment plan, deferred-payment arrangement, or other written billing agreement.
  • Personal funds or other lawful resources, where available.

A provider may continue billing the patient or health plan even when an injury claim is pending. A liability carrier may later consider reasonable, accident-related medical expenses as part of damages, but that does not mean it has accepted fault or agreed to pay every invoice. Coverage, causation, medical necessity, policy terms, and disputed liability can all matter.

Albuquerque patients should also ask providers how balances are being submitted and whether an account has been placed with a billing service. A person should avoid ignoring statements simply because a claim exists. Depending on the circumstances, an attorney may help communicate with providers and identify which records and balances require follow-up.

How Should You Track Health Insurance and Treatment Bills in Albuquerque?

Using health insurance during treatment can help keep care moving, but it creates a documentation task. Explanation-of-benefits statements may show what the plan paid, what amount was applied to a deductible or coinsurance, and what remains disputed or outstanding. Keep those statements with itemized bills, receipts, payment confirmations, and correspondence from the plan or provider.

Readers can review how health insurance reimbursement claims can affect an Albuquerque crash settlement for more information about preserving plan communications and identifying accident-related payments. Reimbursement questions can vary by plan language and circumstances, so a person should not assume that every claimed amount is automatically valid or automatically waived.

Records that can clarify the balance

A practical file may include:

  1. Itemized bills showing the provider, date of service, procedure, and balance.
  2. Explanation-of-benefits statements and health-plan correspondence.
  3. Receipts, canceled-payment records, and payment-plan confirmations.
  4. Prescription, referral, restriction, and appointment records related to the crash.
  5. A communication log listing calls, emails, claim numbers, and unanswered requests.

Medical forms also deserve attention. A standard provider billing form, a health-insurance authorization, and a broad release requested by a liability carrier may serve different purposes. Before signing, readers can review which Albuquerque car accident medical forms deserve careful review. Understanding the scope of a request is especially important when records include unrelated medical history.

What Should You Do While an Albuquerque Crash Claim Is Pending?

Treatment and billing often continue while an insurer investigates. A liability adjuster may ask for records, statements, or updates, but communications with the carrier should be handled thoughtfully. Providing organized information about treatment is different from agreeing that the carrier will pay current bills or accepting an early settlement.

If the claim is delayed, readers may find guidance on what to do when an Albuquerque car accident insurance claim stalls. Keeping copies of requests and responses can help show what information was supplied and when. A clear written status request may also reduce confusion about whether the carrier is investigating coverage, fault, damages, or all three.

Common mistakes to avoid

  • Stopping prescribed or scheduled care solely because a bill is difficult to manage, without discussing the issue with the appropriate medical office.
  • Assuming the other driver’s insurer will pay providers immediately.
  • Paying a bill without keeping proof of payment or an updated balance.
  • Signing a broad medical authorization or release without understanding its scope.
  • Accepting a settlement before considering outstanding bills, reimbursement claims, and possible future care.

Ongoing treatment records may also matter when a claim includes continued or future care. Documentation such as visit summaries, referrals, restrictions, and provider discussions can support an evaluation of evidence supporting future medical costs after an Albuquerque crash. That does not mean a person should pursue unnecessary treatment; medical decisions belong with qualified healthcare professionals.

A settlement may not arrive when the first bills do. Medical recovery, record collection, claim evaluation, and negotiations can take time. The New Mexico personal injury case timeline provides broader context for why these stages may not match a provider’s billing cycle. Before signing, readers should also consider whether to sign an Albuquerque crash settlement release before treatment ends, because a release may affect unresolved claims and future billing questions.

Frequently Asked Questions

Does the at-fault driver’s insurance pay my medical bills immediately?

Usually, a liability carrier does not pay each medical bill as it arrives merely because a claim has been reported. The carrier may still be investigating fault, coverage, and the relationship between treatment and the crash. Depending on the circumstances, available health insurance, medical payments coverage, or a provider arrangement may address bills while the claim is pending. Payment handling can vary by policy and facts.

Can I use health insurance for treatment after an Albuquerque crash?

A person may be able to use available health insurance for accident-related care, subject to the plan’s terms and ordinary cost-sharing. The plan may later raise reimbursement questions about payments connected to a third-party claim. Keep explanation-of-benefits statements, bills, and payment records. Because plan language and applicable rules vary, an attorney may help review the issue in the context of the claim.

What if a medical provider sends my crash bill to collections?

A collection notice should not be ignored. Review whether the balance is accurate, contact the provider or billing service about available arrangements, and preserve all correspondence. Depending on the facts, a lawyer may communicate with the provider while also evaluating the injury claim. Collection rights and billing-dispute rules can involve issues beyond personal injury law, so situation-specific advice may be appropriate.

Should I settle my claim while I still have medical bills?

An early settlement may require a release that affects claims not yet resolved, including future treatment or outstanding reimbursement issues. The right decision depends on the treatment status, available records, damages, coverage, and terms of the proposed release. Before accepting or signing, a person may benefit from having the offer, bills, and related documents reviewed by a qualified attorney.

How The Crecca Law Firm Can Help

The Crecca Law Firm is dedicated to helping Albuquerque injury clients understand the practical issues that arise before a car accident settlement arrives. The firm can evaluate available insurance information, treatment records, bills, provider communications, and correspondence with the liability carrier. Its approach is focused on clear communication, careful documentation, and protecting the client’s ability to make informed decisions as the claim develops.

If you are dealing with medical treatment and unpaid or disputed bills after a crash, contact The Crecca Law Firm for a free consultation or case evaluation. The firm is ready to evaluate your situation and discuss your legal options without promising a particular result.

The information in this article is for educational purposes only and does not constitute legal advice. Contact a qualified attorney licensed in Albuquerque for advice specific to your situation.
https://thecreccalawfirm.com/wp-content/uploads/2026/10/albuquerque-crash-medical-bills-before-settlement-5423-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-06 09:29:532026-10-06 09:32:59Who Pays Albuquerque Crash Medical Bills Before Settlement?
Recorded statement insurance company after car accident Albuquerque scene near parked vehicles

Which Questions Can an Albuquerque Adjuster Ask on Record?

October 6, 2026

An adjuster calls after your Albuquerque crash and asks to record a few questions. The request may sound routine, but a recorded statement can become part of the claim file and may later be compared with other evidence. The first question is not simply whether to answer—it is who is asking, and under what insurance policy relationship. The Crecca Law Firm provides documents and steps for an Albuquerque recorded statement to help readers understand the preparation process.

In general, a statement to your own insurer may involve cooperation duties in the policy, while a statement to the other driver’s insurer is usually part of that company’s investigation of a claim against its insured. Those situations are not identical. This guide explains what a recorded statement is, what an adjuster may ask, how to avoid guessing, and why people handling an Albuquerque accident claim may benefit from understanding the request before responding.

What Is a Recorded Statement to an Insurance Company After a Car Accident in Albuquerque?

A recorded statement is an interview preserved in an audio file, transcript, or written summary. An insurance adjuster may ask about the collision, the vehicles, road conditions, injuries, medical care, property damage, and events before or after impact. The adjuster may also ask whether you took photographs, spoke with witnesses, or reported the crash to law enforcement.

The purpose is generally to gather information for the insurer’s claim investigation. A recorded interview is not the same as a court deposition, and an adjuster is not a neutral decision-maker. The insurer may use the information to evaluate coverage, liability, damages, or consistency with other records. That does not mean every request is improper, but it does mean the scope and context deserve attention.

Identify the insurer and policy relationship

Before discussing the collision, a person may want to confirm the caller’s name, the insurance company, the claim number, and the insured person or vehicle involved. Ask whether the caller represents your own insurer, the other driver’s insurer, an employer, a vehicle owner, or another potentially involved party.

Policy relationships can become complicated. For example, the driver, vehicle owner, injured person, and policyholder may be different people. This can occur in a borrowed-vehicle crash, where understanding insurance coverage after a borrowed-car accident in Albuquerque may be especially important.

Your own insurer and the other driver’s insurer

A policy may require cooperation with your own carrier, depending on its terms and the circumstances. A request from the other driver’s insurer is different because that company may be evaluating a claim against its insured. Whether you have a legal duty to provide a statement can depend on the policy, the parties, and the facts. An attorney can review those issues when the answer is unclear.

What May an Adjuster Ask During a Car Accident Recorded Statement?

An insurance adjuster recorded interview may cover both simple facts and issues that require careful wording. Common topics include:

  • Your name, contact information, and role in the crash.
  • The date, time, location, direction of travel, and weather or road conditions.
  • What you saw, heard, or did immediately before and after impact.
  • Vehicle damage, photographs, witnesses, and any police or incident report.
  • Symptoms, medical visits, prior injuries, work limitations, and treatment.
  • Other insurance policies, household vehicles, or possible passengers.

The exact questions vary. A broad question about everything that happened before a collision may call for clarification. A question about whether you were “hurt” may also be unclear if symptoms developed later or if the person is still being evaluated. Readers can review guidance about Albuquerque crash questions that need clarification before responding to confusing, compound, or overly broad questions.

Answer from memory, not assumptions

Accuracy matters more than sounding certain. If you do not remember a speed, distance, timing detail, or sequence, it is generally better to say that you do not recall than to estimate. Avoid agreeing with a question merely because it seems to suggest an answer. You may ask the adjuster to repeat or narrow the question, request a pause, or explain that you need to check a record.

A person can also distinguish firsthand knowledge from information learned later. For example, “I saw the vehicle move into my lane” is different from “Someone told me the other driver was looking at a phone.” Do not present assumptions, conclusions, or another person’s account as something personally observed.

A recorded statement is not a medical authorization

An interview and a medical-record release are separate requests. An insurer may ask for a recorded account and separately present a form authorizing access to medical records. Those documents can have different effects and different scopes. Before signing, consider whether the authorization is limited to accident-related care or instead seeks a much broader history. The distinction is discussed further in Albuquerque car accident medical forms and authorizations.

How Should You Prepare Before Giving a Recorded Statement?

Preparation does not mean memorizing a script or shaping facts to fit a claim. It means understanding the request, organizing information you actually know, and identifying questions that may need clarification. In Albuquerque, available materials might include an APD crash report, photographs, vehicle-damage records, medical bills, appointment information, and communications with insurers. The relevance and availability of each item depend on the circumstances.

Before an interview, a person may consider the following general steps:

  1. Confirm the caller’s identity, insurer, claim number, and relationship to the claim.
  2. Ask what subjects the adjuster wants to cover and whether the conversation will be recorded.
  3. Review basic dates, locations, photographs, and reports without guessing beyond the records.
  4. Make a note of facts that remain uncertain, such as exact speed or timing.
  5. Avoid discussing unrelated medical history or making conclusions about legal fault.
  6. Consider whether legal guidance is appropriate before speaking with an opposing insurer.

The best evidence after a car accident claim may include photographs, witness information, reports, treatment records, and other materials. Those records can help a person give a careful account, but they do not replace personal knowledge. A person should not alter, discard, or manufacture evidence.

Common mistakes to avoid

People sometimes make avoidable errors by treating an adjuster’s call as an informal conversation. Potential problems include volunteering speculation, minimizing symptoms, exaggerating certainty, answering a different question than the one asked, or discussing settlement before the claim is understood. Another mistake is assuming that a friendly tone means the caller represents the injured person’s interests.

A person who realizes that an answer was inaccurate should not try to conceal the error. Depending on the circumstances, an attorney may help evaluate whether and how to correct the record. Serious injuries, disputed responsibility, multiple insurers, uncertain coverage, or a request from an opposing carrier are situations in which choosing Albuquerque accident lawyers after a crash may be worth considering.

Frequently Asked Questions

Can the other driver’s insurer record my statement without my permission?

A third-party insurer may ask for a recorded statement, but whether you must provide one depends on the circumstances, any applicable policy language, and the nature of the claim. A request is not necessarily the same as a legal requirement. You may ask why the statement is needed, who will receive it, and whether it will be recorded. When liability, injuries, or coverage are disputed, an attorney can help assess the request.

What if I do not remember an important detail about the crash?

It is generally safer to acknowledge uncertainty than to fill a memory gap with an estimate presented as fact. You can say that you do not recall, explain what you do remember, and identify records that may help confirm details. Avoid guessing about speed, distance, timing, or another person’s actions. If you later discover that an answer was inaccurate, consider obtaining legal guidance about the appropriate way to address it.

Should I discuss my prior medical history with the other insurer?

An adjuster may ask about prior conditions or treatment when evaluating an injury claim, but the relevance and scope of those questions can vary. A recorded statement is not the same as permission to obtain every medical record. Avoid volunteering unrelated details or making medical conclusions. Separate medical authorizations may also require careful review. A licensed attorney can explain how these issues may apply to the claim’s facts.

Does a recorded statement determine who was at fault in Albuquerque?

No single statement automatically determines fault. An insurer may compare the interview with photographs, crash reports, witness accounts, vehicle damage, medical records, and other evidence. New Mexico’s rules concerning responsibility and damages may apply differently depending on the facts, and laws can change. A statement can be considered as part of the investigation, but it is not the only source of information.

How The Crecca Law Firm Can Help

The Crecca Law Firm is dedicated to helping Albuquerque crash victims understand the claim process and the significance of insurer communications. The firm can evaluate questions about who is requesting a statement, what policy relationship may exist, what information is documented, and whether the circumstances call for additional guidance. Its approach is focused on careful fact review, clear communication, and protecting the client’s ability to make informed decisions.

If an insurer has requested a recorded interview after your car accident, contact The Crecca Law Firm for a free consultation or case evaluation. The team is committed to fighting for your rights and is ready to evaluate your situation without promising a particular outcome.

The information in this article is for educational purposes only and does not constitute legal advice. Contact a qualified attorney licensed in Albuquerque for advice specific to your situation.
https://thecreccalawfirm.com/wp-content/uploads/2026/10/which-questions-can-an-albuquerque-adjuster-ask-on-record-5405-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-06 08:39:242026-10-06 08:47:50Which Questions Can an Albuquerque Adjuster Ask on Record?
Albuquerque police crash report and disputed car accident fault evidence

When Does an Albuquerque Crash Report Influence Fault?

October 5, 2026

After a collision, many drivers assume the police report settles the question of fault. But what happens when the report leaves out a witness, misunderstands the impact, or says you caused the accident even though other evidence points elsewhere? For someone searching whether an Albuquerque car accident police report decides fault, the short answer is usually no: the report may be important, but it is not automatically the final word in a civil claim. The Crecca Law Firm helps readers understand how to assess that evidence without treating an initial conclusion as a guaranteed determination.

This article explains what an officer’s report may show, how citations and statements can affect an insurance dispute, what to do if the report appears incomplete or inaccurate, and how to communicate with insurers when facts remain disputed.

For additional guidance, see fixing errors in an Albuquerque car accident police report.

Does an Albuquerque Police Report Decide Fault in a Car Accident?

A crash report is generally one piece of evidence among many. An officer may record statements from drivers and witnesses, note visible damage, prepare a diagram, document road conditions, and state an opinion about contributing factors. Those observations can be useful, particularly when the report was prepared soon after the collision.

However, an officer may not have seen the crash happen. The report may rely on brief interviews, limited physical evidence, or information available at the scene. A diagram may simplify lane positions or movement. A citation may indicate that an officer believed a traffic rule was violated, but a traffic citation and a civil car accident claim are not identical proceedings. The citation does not automatically establish every fact needed to resolve financial responsibility for injuries or property damage.

What information in a report may matter?

Review the report for:

  • Each driver’s version of events and whether it is accurately recorded.
  • Witness names, contact information, and descriptions of what they observed.
  • Officer observations about damage, debris, skid marks, traffic controls, and road conditions.
  • The diagram, measurements, narrative, and any listed contributing factors.
  • Citations, statements about admissions, and references to video or other evidence.

A report that says a driver caused the crash may influence an adjuster, but insurers and courts may also consider photographs, vehicle damage, video, medical records, testimony, and other evidence. New Mexico rules concerning fault and evidence can be fact-specific and may change, so local legal review may be useful when the report conflicts with the rest of the record.

What Should You Do If an Albuquerque Accident Report Is Wrong?

Start by obtaining the complete report from the investigating agency, such as the Albuquerque Police Department when it handled the collision. Depending on where the crash occurred, another law-enforcement agency may have prepared it. Read the narrative, diagram, witness section, citation information, and any supplemental pages rather than relying only on an insurer’s summary.

If the report contains a factual error or omission, identify the issue precisely. Separate an objective mistake—such as an incorrect vehicle description or missing witness—from a disagreement with the officer’s interpretation. Ask the investigating agency whether it has a process for submitting additional information or requesting a supplemental report. A correction is not guaranteed, and an agency may not change an officer’s conclusion simply because a driver disagrees with it. More information about fixing errors in an Albuquerque car accident police report may help you understand the distinction.

Preserve independent proof before it disappears

A report can be supplemented by evidence created independently of the officer’s initial investigation. Consider preserving, when available and lawfully obtained:

  1. Photographs or video of vehicles, the roadway, traffic controls, lighting, and visible damage.
  2. Names and contact information for witnesses, along with notes about what each person personally observed.
  3. Dashcam, nearby business-camera, or residential-camera leads before recordings are overwritten.
  4. Repair estimates, inspection photographs, towing records, and contemporaneous notes about the collision.
  5. Phone or location information only through appropriate legal and privacy channels.

This is why preserving the strongest evidence after a car accident can matter when the report does not tell the full story.

How Evidence and Insurer Communications Can Challenge a Report

The strongest response to an unfavorable report is usually a clear, organized account supported by reliable evidence—not an exaggerated accusation that the officer acted improperly. Look for specific conflicts: a witness who describes a different light color, damage that appears inconsistent with the diagram, a camera that may show lane movement, or a statement that does not reflect what a driver remembers saying.

Intersection crashes in Albuquerque often require close attention to signal timing, sightlines, turning paths, lane position, and right-of-way facts. Conditions can change quickly after a collision, so preserving evidence from an Albuquerque intersection crash may help maintain details that a short diagram cannot capture.

Communicate carefully with an insurer

When an adjuster asks about the report, provide accurate firsthand facts and distinguish memory from assumption. Avoid adopting a disputed conclusion merely because it appears in the report. It is also unwise to guess about speed, distance, signal timing, or another driver’s actions.

Before giving a recorded statement, consider preparing for an Albuquerque recorded insurance statement. If a question is unclear or assumes a fact you dispute, ask for clarification. These questions to clarify before answering an Albuquerque crash adjuster can help a driver understand what information is being requested without overstating uncertain facts.

A driver should also avoid deleting messages, altering photographs, repairing or disposing of a vehicle before documenting its condition, or posting a speculative account publicly. If the report, evidence, and insurer’s position conflict, an attorney may assess how New Mexico’s fault principles and available proof apply to the particular claim.

Frequently Asked Questions

Can an officer’s opinion in a crash report be challenged?

Yes, an officer’s opinion may be challenged with evidence that provides a different account, such as witness testimony, photographs, video, vehicle damage, or additional records. Challenging an opinion does not necessarily mean the report will be rewritten. The practical question is how the complete evidence affects an insurer’s evaluation or a later civil proceeding. The relevance and weight of each item depend on the circumstances and applicable New Mexico law.

What if the police report leaves out my witness?

Obtain the report and check whether the witness was listed under another name or in a supplemental page. Preserve the witness’s contact information and ask what the witness personally saw, rather than coaching the person about fault. You may provide the information to the investigating agency or insurer, depending on the situation. An attorney can explain how witness evidence may be documented and used in a disputed Albuquerque claim.

Does a traffic citation prove civil liability for the crash?

Not automatically. A citation may be relevant because it reflects an officer’s belief that a traffic rule was violated, but a civil claim can involve additional questions about causation, damages, and the conduct of other people. The effect of a citation may depend on the underlying facts and applicable New Mexico procedures. Readers should avoid assuming that paying, contesting, or receiving a citation alone resolves the civil claim.

Should I tell the insurer that I disagree with the report?

You can accurately explain that the report does not reflect your account, but avoid presenting uncertain facts as established or making statements about matters you did not personally observe. Keep communications factual and preserve supporting evidence. If an insurer requests a recorded statement or relies heavily on an unfavorable report, Albuquerque auto accident lawyers who can evaluate disputed fault may be able to review the situation and discuss available options.

How The Crecca Law Firm Can Help

The Crecca Law Firm is dedicated to helping Albuquerque crash victims understand how police reports, citations, witness accounts, physical evidence, and insurance communications may affect a claim. The firm can review whether an accident report appears incomplete, organize evidence that may support a different account, and help evaluate disputed fault under applicable New Mexico principles. Each case depends on its specific facts, and no legal review guarantees a particular result.

If a report appears inaccurate or an insurer is relying on it to question your claim, contact The Crecca Law Firm for a free consultation or case evaluation. The team is committed to fighting for your rights and is ready to evaluate your situation.

The information in this article is for educational purposes only and does not constitute legal advice. Contact a qualified attorney licensed in Albuquerque for advice specific to your situation.
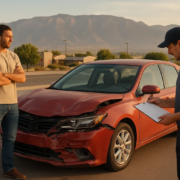
https://thecreccalawfirm.com/wp-content/uploads/2026/10/when-does-an-albuquerque-crash-report-influence-fault-5306-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-05 09:53:282026-10-05 09:59:18When Does an Albuquerque Crash Report Influence Fault?
Albuquerque totaled car insurance valuation review beside a damaged vehicle

Can Loan Issues Change Your Albuquerque Total-Loss Value?

October 5, 2026

A totaled vehicle can create a practical problem almost immediately: you may need transportation while also deciding whether an insurer’s valuation is accurate. An Albuquerque totaled car insurance valuation generally aims to estimate the vehicle’s actual cash value shortly before the crash, but the calculation may depend on details that are easy to overlook. For a broader explanation of the process, see reviewing an Albuquerque total-loss vehicle valuation.

The Crecca Law Firm provides this guide to help Albuquerque drivers understand the numbers before accepting a payment or signing paperwork. It covers how insurers compare vehicles, which options and fees may matter, how loan balances and replacement transportation fit into the picture, and what records can support a disagreement.

How Is an Albuquerque Totaled Car Insurance Valuation Calculated?

When an insurer treats a vehicle as a total loss, the central question is usually what the car was worth immediately before the collision—not what it would have been worth after repairs or what it cost when purchased. This is commonly called actual cash value, although policy language and the claim’s circumstances can affect the analysis.

What an insurer may consider

A valuation report may review:

  • Year, make, model, trim, and drivetrain
  • Mileage and the vehicle’s pre-crash condition
  • Factory options, packages, and documented upgrades
  • Comparable vehicles available in the relevant market
  • Prior damage, maintenance history, and title or history information
  • Applicable taxes, registration-related charges, or other policy-approved fees
  • Salvage value or other deductions, depending on the proposed resolution

The comparable vehicles should be reasonably similar. A base model may not be a fair comparison for a higher trim with all-wheel drive, a towing package, upgraded technology, or other equipment. Mileage differences can also affect the estimate, as can condition ratings that do not match photographs or maintenance records.

An Albuquerque driver can review what to do before an insurer inspects crash damage. Generally, photographs, repair estimates, service records, and purchase documents should be preserved. Repairing, altering, or disposing of the vehicle before a fair inspection may make it harder to document the loss.

What Should You Check in a Total-Loss Valuation?

A valuation deserves more than a quick look at the final dollar figure. Ask whether the report describes your actual vehicle and whether its adjustments are supported by reliable information. In New Mexico, policy terms and the facts of the claim matter, and insurance practices can vary. The New Mexico Office of the Superintendent of Insurance may provide general consumer information, but it does not replace advice about a specific dispute.

Use this checklist when reviewing the report:

  1. Confirm the vehicle description. Check the VIN, model year, trim, drivetrain, mileage, and listed condition. A mistake in any of these fields can affect the comparison.
  2. Look for omitted equipment. Identify factory options, packages, recent upgrades, accessories, and safety or technology features. Gather invoices, photographs, window-sticker information, or service records where available.
  3. Evaluate the comparables. Check location, mileage, trim, condition, and availability. A listing that is not genuinely comparable may not provide a useful benchmark.
  4. Review adjustments. Look for unexplained deductions or credits tied to mileage, condition, prior damage, options, or market differences.
  5. Separate vehicle value from other costs. Determine whether taxes, title-related charges, registration expenses, towing, storage, or transportation costs are included, excluded, or handled under separate policy provisions.
  6. Check salvage and lien information. Confirm whether a salvage deduction applies and whether the payment is being issued jointly with a lender.

The valuation report may not account for every expense caused by the crash. For example, replacement transportation can involve rental vehicles, rideshare charges, or other documented costs. Keeping receipts may help clarify what was paid and whether the policy or another party’s coverage addresses those expenses. Review information about recovering rental car and other transportation expenses after a crash for related considerations.

What Can You Do About a Disputed Albuquerque Total-Loss Valuation?

A disagreement does not necessarily mean the insurer acted improperly, but it does mean the assumptions should be examined carefully. A low figure may result from an incorrect trim level, missing options, unsuitable comparables, an inaccurate condition rating, or deductions that are not explained clearly. It may also reflect a disagreement about what the policy covers.

Start by organizing a written response rather than relying only on a phone conversation. Identify each disputed item and attach supporting material, such as photographs, dealer listings, maintenance invoices, vehicle-history records, and comparable-vehicle research. Keep copies of emails, reports, estimates, and claim notes. These records can help an attorney assess whether the issue is valuation, coverage, causation, or another part of the claim.

The article on why an Albuquerque crash settlement offer may be too low discusses ways to examine an offer that may omit losses or rely on disputed information. If the insurer refuses to reconsider the number, additional documentation may be useful. See evidence to gather after an Albuquerque crash claim denial for examples of records that may support further review.

A loan balance creates a separate financial issue. The insurer’s valuation generally concerns the vehicle, while the lender’s payoff depends on the loan contract and account balance. If the payoff exceeds the insurance payment, the remaining balance may not disappear automatically. Gap coverage, if purchased and applicable, may address some of that difference. Because loan terms and insurance policies vary, review the proposed payoff carefully.

Replacement transportation also deserves attention. Keep rental agreements, rideshare receipts, public-transit records, and communications about transportation coverage. Before accepting a check, read any release carefully. Reviewing an Albuquerque crash settlement release before signing may be important because a document that appears to resolve property damage could potentially affect other claims, depending on its wording.

Frequently Asked Questions

Does a totaled car’s purchase price determine its value after a crash?

Usually, the original purchase price is only one piece of background information. A total-loss valuation generally focuses on the vehicle’s pre-crash actual cash value, including its age, mileage, condition, equipment, and comparable vehicles. A recent purchase invoice may help document the vehicle’s features or condition, but it does not necessarily establish the amount payable under a policy. The policy language and available evidence remain important.

Can I keep my totaled vehicle in New Mexico?

In some situations, an owner may ask to retain a damaged vehicle, but the payment may be adjusted for salvage value and title or registration requirements may apply. The exact process depends on the insurer, the vehicle’s status, and New Mexico requirements. Before making that choice, consider repair costs, safety concerns, storage, inspection issues, and whether the vehicle can legally be operated.

What if my insurer’s comparable cars are in another market?

Location can matter because vehicle prices and availability may differ between markets. A comparison should be reasonably similar in model, trim, mileage, condition, and equipment. If the report relies on vehicles that are not realistically comparable to the Albuquerque market, gather better-supported listings and explain the differences in writing. An attorney may help evaluate whether the report’s methodology is persuasive under the applicable policy and facts.

Does accepting a property-damage payment end every claim?

Not necessarily, but the answer depends on the paperwork. Some payments or releases may address only specified property damage, while broader language could affect injury, transportation, or other claims. Read the proposed release before signing and identify exactly what it resolves. If the wording is unclear or multiple losses remain open, a licensed attorney may review the document and explain potential concerns.

How The Crecca Law Firm Can Help

The Crecca Law Firm is dedicated to helping Albuquerque crash victims understand the documents and valuation issues that can arise after a total loss. The firm can evaluate the reported vehicle details, comparable vehicles, options, condition adjustments, lender information, transportation expenses, and communications with the insurer. When a valuation or release raises concerns, the team is committed to fighting for the client’s rights while explaining available options in clear terms. Contact The Crecca Law Firm for a free consultation or case evaluation about your situation.

The information in this article is for educational purposes only and does not constitute legal advice. Contact a qualified attorney licensed in Albuquerque for advice specific to your situation.
https://thecreccalawfirm.com/wp-content/uploads/2026/10/can-loan-issues-change-your-albuquerque-total-loss-value-5266-featured-publisher.webp 1024 1536 publisher https://thecreccalawfirm.com/wp-content/uploads/2023/03/logo-300x87.png publisher2026-10-05 08:08:302026-10-05 08:08:30Can Loan Issues Change Your Albuquerque Total-Loss Value?
Page 1 of 14123›»

Recent Posts

  • What Might Discovery Ask in an Albuquerque Lawsuit?
  • When Should Multiple Claimants Review Albuquerque Limits?
  • What Fees Does an Albuquerque Car Accident Lawyer Charge?
  • What Shapes an Albuquerque Car Accident Claim Timeline?
  • Can Albuquerque Freelancers Claim Lost Income After Crashes?

Contact Us

ADDRESS

3200 Monte Vista Blvd NE,
Albuquerque, NM 87106

PHONE

505-766-9999

EMAIL

info@thecreccalawfirm.com

Contact Us


    Please prove you are human by selecting the star.


    Popular Links

    • Home
    • About Us
    • Blog

    Practice Areas

    • Asbestos Cases
    • Nursing Home Negligence
    • Wrongful Death
    • Phone

      505-766-9999

    • Email

      info@thecreccalawfirm.com

    • Address

      3200 Monte Vista Blvd NE,
      Albuquerque, NM 87106

    The Crecca Law Firm is located in Albuquerque and represents clients and takes injury claim cases throughout the entire state of New Mexico.
    The information on this Law Firm website is for general information purposes only. Nothing on this or associated pages, documents, comments, answers, emails, or other communications should be taken as legal advice for any individual case or situation. This information on this website is not intended to create, and receipt or viewing of this information does not constitute, an attorney-client relationship.
    Copyright 2023 The Crecca Law Firm | All Rights Reserved |
    Legal Marketing Solutions by USAttorneys.com
    • Facebook
    • Areas Served
    • Sitemap
    Scroll to top